
SG · gst
Singapore GST and service charge calculator: the order matters
For an established taxable Singapore restaurant bill of SGD 100 before charges, an assumed 10% service charge makes SGD 110. Applying 9% GST to SGD 110 gives SGD 9.90 GST and SGD 119.90 total. The service-charge percentage is an example, not a statutory requirement.
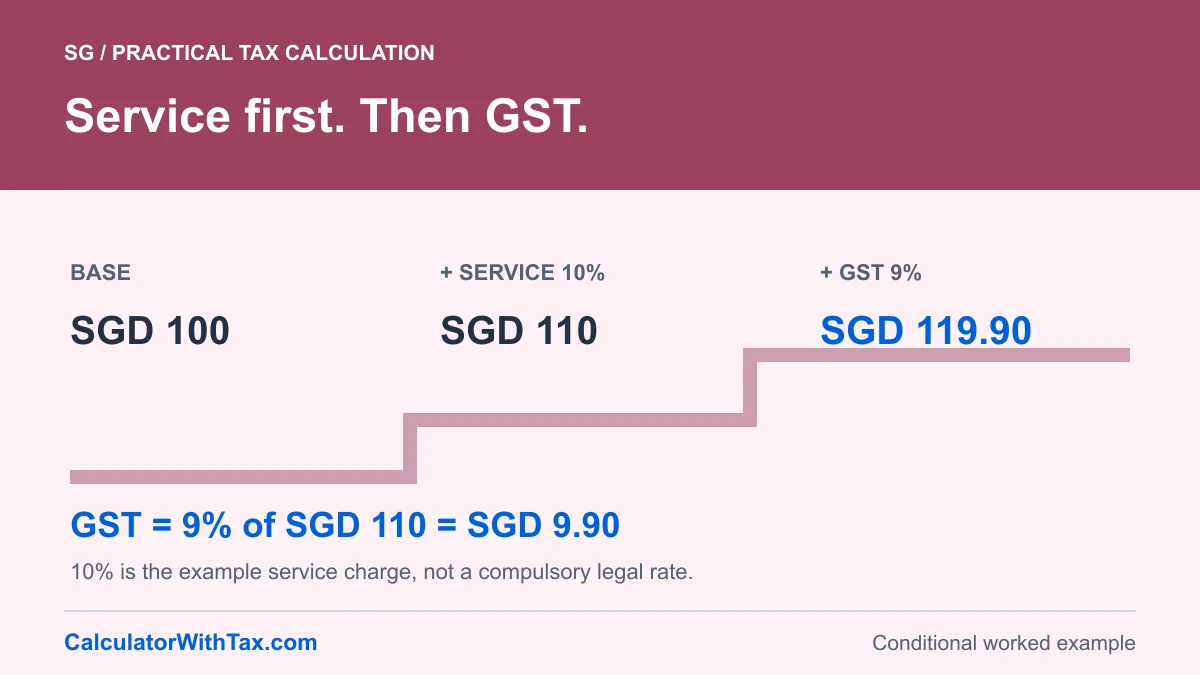
Apply GST to the amount including service charge
For an ordinary Singapore restaurant bill already established as taxable, the calculation sequence matters: start with the amount before charges, add the applicable service charge, then calculate GST on that combined amount. Do not add 10% and 9% to the original menu amount as though both had the same base.
At an assumed 10% service charge and the 9% GST reference, SGD 100 becomes SGD 119.90, not SGD 119.00. This is an arithmetic illustration of a known taxable bill. It does not determine registration, classify a supply or prove that a particular establishment charges 10% service.
IRAS’s hotel and food-and-beverage guidance gives the same SGD 100, SGD 10 service and SGD 9.90 GST sequence. It also makes clear that imposing a service charge is a business decision. The service percentage must therefore be an explicit assumption rather than a fixed tax rule.
Follow the SGD 100 bill step by step
Begin with SGD 100 before service and GST. An assumed 10% service charge adds SGD 10. The resulting GST base is SGD 110. At 9%, GST is SGD 9.90, so the completed amount is SGD 119.90.
There are three different quantities: the original charge, the service-inclusive before-GST base and the GST-inclusive total. Labeling all three simply as “subtotal” makes mistakes harder to detect. A useful bill should let the reader identify which amount each percentage uses.
Add service charge before GST
One established Singapore 9% taxable supply. The service percentage is an input, not a mandatory statutory charge. No cash-payment rounding or registration decision.
GST = (price + service charge) x 9/100 under the established taxable assumption.
- Including service and GST
- SGD 119.90
Price before charges: SGD 100.00; Service charge: SGD 10.00; GST on both amounts: SGD 9.90; Final price: SGD 119.90
| Starting assumptions | Tax in the stated amount | Scenario result |
|---|---|---|
| Service charge and GST apply: SGD 100.00; 10% | SGD 9.90 | Including service and GST: SGD 119.90 |
| Service charge and GST apply: SGD 200.00; 10% | SGD 19.80 | Including service and GST: SGD 239.80 |
| Service charge and GST apply: SGD 100.00; 0% | SGD 9.00 | Including service and GST: SGD 109.00 |
The adjustable example keeps GST at the established 9% reference and lets you change the commercial service-charge assumption. Its result is a single-treatment calculation, not an invoice-compliance or cash-rounding service. Reset restores the disclosed SGD 100 and 10% example rather than a hidden location-based rate.
Why adding the percentages misses part of the GST
The incorrect shortcut calculates SGD 10 service and SGD 9 GST from the same SGD 100 starting amount, producing SGD 119. It omits GST on the SGD 10 service charge. Nine percent of that omitted amount is SGD 0.90, explaining the difference from SGD 119.90.
Under these exact assumptions and before any cent rounding, the combined multiplier is 1.10 multiplied by 1.09, or 1.199. The increase is therefore 19.9% of the original amount. That is not a new statutory GST rate; it is the combined effect of a particular commercial service charge and the tax applied to the resulting base.
If the establishment charges a different service percentage, the combined increase changes too. Do not memorize 19.9% as a universal Singapore restaurant surcharge. Read the actual terms and keep the order of operations visible.
Compare a larger bill and a no-service case
With SGD 200 before charges and the same assumed 10% service, the service amount is SGD 20. The GST base is SGD 220, GST is SGD 19.80 and the final amount is SGD 239.80. The worked table derives those figures from the same decimal calculation helper as the adjustable example.
With SGD 100 before GST and no service charge in this illustration, the GST base remains SGD 100. GST is SGD 9 and the total is SGD 109. The absence of a service charge does not make an otherwise taxable supply GST-free.
The converse also matters: seeing a service charge does not prove that every underlying supply has the same tax treatment. The examples assume that classification is settled and contain no exempt, zero-rated or mixed components.
Read what the displayed price already includes
A menu amount described as before service and GST is a different starting point from a final GST-inclusive bill. Adding the charges again to an already final amount double-counts them. Before using a calculator, identify whether the number is the menu base, service-inclusive subtotal or final payable total.
IRAS’s price-display guidance generally requires GST-inclusive public prices and describes a conditional treatment for qualifying hotels and food-and-beverage establishments levying service charge with the required notice. It is not general permission for every business to advertise a tax-exclusive price.
A “++” label is not enough to establish all amounts and conditions. Check the disclosed service percentage and whether the quoted price is actually before both additions. The calculation assumes that starting basis has been confirmed.
Extracting GST is different from recovering the menu base
If a final amount is known to include only the assumed 9% GST on its entire before-GST base, the GST fraction is 9 over 109. In the SGD 119.90 example, that identifies SGD 9.90 GST and leaves SGD 110 before GST.
That SGD 110 still includes the SGD 10 service charge. It is not the original SGD 100 menu amount. Recovering the menu amount additionally requires knowing the service-charge basis and percentage. A GST-only reverse calculation cannot infer those commercial terms from a payment total.
The Singapore GST guide explains adding and extracting GST from a known single-treatment amount. Use it for the tax component, while keeping service-charge reconstruction as a separate step based on reliable bill information.
Watch the boundary between rounding and classification
The examples round monetary components to cents using the disclosed calculation sequence. A small fractional result can change when several lines are rounded separately rather than combined. That is a rounding-scope question, not a reason to apply GST only to the menu amount.
Cash settlement is not included here. Nor does the example allocate shared bills between diners, assess a voluntary tip, validate a merchant’s registration or produce a compliant tax invoice. Those features require more facts than this bounded comparison accepts.
A quick restaurant-bill check
- Confirm what the stated price already includes.
- Read the actual service-charge percentage and its calculation base.
- Add that service amount to the appropriate before-GST amount.
- Apply the established GST treatment to the resulting base.
- Reconcile the final bill before considering any separate settlement adjustment.
Use the figures to explain an already established scenario, not to select the most convenient tax treatment. A transparent calculator is useful precisely because it shows where the service ends and the GST calculation begins.
Frequently asked questions
Is Singapore GST calculated before or after service charge?
For the ordinary taxable food-and-beverage example described by IRAS, GST applies to the amount including the service charge. Calculate that charge first, then GST on the combined base.
Is 10% service charge compulsory?
No. The 10% used here is an assumed commercial charge, not a statutory service-charge rate. Use the establishment's actual disclosed terms.
Why is SGD 100 plus 10% service and 9% GST SGD 119.90?
The service charge is SGD 10. GST is 9% of SGD 110, or SGD 9.90, giving SGD 119.90. Adding both percentages only to SGD 100 would omit SGD 0.90 GST on the service charge.
Can every Singapore business advertise GST-exclusive prices?
No. IRAS generally requires GST-inclusive public prices, with a conditional treatment for qualifying hotels and food-and-beverage establishments levying service charge and displaying the required notice. Check the applicable conditions.
Does the result include cash rounding or a voluntary tip?
No. The example calculates only the stated service charge and GST. Cash settlement, voluntary gratuities and other adjustments are separate.
Check a separately established amount
Use one confirmed taxable amount and the applicable percentage. The manual calculator does not select a rate or classify the transaction.
Open the manual calculator