
GB · business-workflows
VAT inclusive vs exclusive: compare UK quotes on equal terms
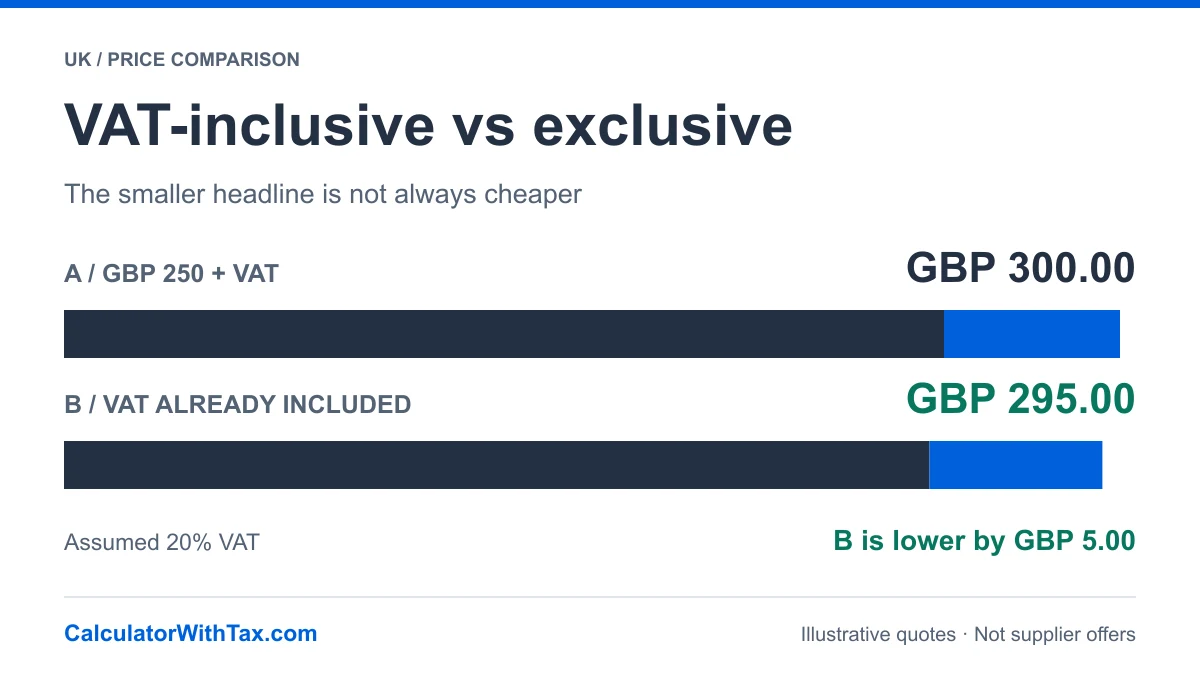
VAT exclusive means before VAT; VAT inclusive means VAT is already in the price. At an assumed 20%, GBP 250 exclusive becomes GBP 300, so a comparable GBP 295 inclusive offer is lower by GBP 5.
VAT inclusive and exclusive: the quick distinction
Exclusive describes the amount before VAT. Inclusive describes the amount with VAT already included. For a payable-price comparison, bring the exclusive quote up to its inclusive total; do not add VAT again to the inclusive offer.
This guide is about choosing a consistent quote-comparison basis, not another list of VAT formulas. Confirm that the two offers cover the same supply and use the correct treatment first. The examples assume 20% for an ordinary UK supply; HMRC’s rate page distinguishes standard, reduced and zero rates. A familiar percentage does not classify a sale.
Compare the payable figures, not the headlines
A quote labelled GBP 250 plus VAT and another labelled GBP 295 including VAT do not start on equal terms. The first excludes a component that the second already contains. Comparing 250 directly with 295 can therefore reverse the apparent winner.
For the synthetic comparison below, assume both quotes cover the same ordinary supply and that a 20% treatment has already been established. Quote A becomes GBP 300 including GBP 50 VAT. Quote B remains GBP 295, with GBP 49.17 VAT and GBP 245.83 before VAT under this calculator’s tax-first cent display. Quote B has the lower inclusive total. These are arithmetic examples, not real supplier offers.
Compare your two quotes
Assumed ordinary UK supply at 20%. Synthetic examples, not actual offers or a tax-eligibility decision.
One already-classified amount per quote, assumed 20%; no currency conversion. Maximum 1,000,000,000,000 per input, two decimal places. Inputs stay on this device.
Quote B is lower by GBP 5.00 on the stated tax basis.
Quote A including VATGBP 300.00
Quote B including VATGBP 295.00
Country-engine results. Other charges and tax recovery are not calculated.
| Quote | Before VAT | VAT | Including VAT |
|---|---|---|---|
| A · exclusive input | GBP 250.00 | GBP 50.00 | GBP 300.00 |
| B · inclusive input | GBP 245.83 | GBP 49.17 | GBP 295.00 |
Quote B would match Quote A at an inclusive price of GBP 300.00, with all other terms equal. A lower price is not a recommendation to choose a supplier.
The break-even price is GBP 300 including VAT: that is where Quote B would match Quote A before any other charges. Below it, B has the smaller total; above it, A does. The displayed difference is not a discount percentage or a recommendation about the supplier’s quality.
Turn a plus-VAT quote into a comparable total
Use the exclusive input when the starting figure is before VAT. The UK VAT calculator adds the tax component after you select the applicable treatment. GOV.UK explains the distinction between VAT-inclusive and VAT-exclusive prices; the classification and any right to reclaim VAT are separate questions.
For this example:
VAT = round(250 × 20 ÷ 100) = 50.00
Comparable total = 250.00 + 50.00 = 300.00
Do not add VAT again to Quote B. Its stated inclusive total is the comparison figure unless other charges change the scope.
A delivery charge can reverse the result
Now suppose A also has GBP 10 delivery before VAT, while B adds GBP 18 delivery including VAT. For this synthetic case, assume the delivered amounts have already been established as one amount at the same 20% treatment. This does not decide the VAT treatment of delivery for a real transaction.
A’s new exclusive amount is GBP 260, making GBP 312 inclusive. B’s new inclusive amount is GBP 313. A is now lower by GBP 1, reversing the first comparison. Merely copying the headline prices into a calculator would have missed the change.
Delivery changes the comparison
Synthetic delivered totals: A has GBP 10 extra before VAT; B has GBP 18 extra including VAT. All amounts already established at the same assumed 20% treatment. Synthetic examples, not actual offers or a tax-eligibility decision.
Quote A is lower by GBP 1.00 on the stated tax basis.
Quote A including VATGBP 312.00
Quote B including VATGBP 313.00
Country-engine results. Other charges and tax recovery are not calculated.
| Quote | Before VAT | VAT | Including VAT |
|---|---|---|---|
| A · exclusive input | GBP 260.00 | GBP 52.00 | GBP 312.00 |
| B · inclusive input | GBP 260.83 | GBP 52.17 | GBP 313.00 |
Quote B would match Quote A at an inclusive price of GBP 312.00, with all other terms equal. A lower price is not a recommendation to choose a supplier.
Compare the underlying amounts when that is useful
If you also need the exclusive amounts, extract VAT from each inclusive figure using the same treatment. At 20%, the included fraction is 20/120, not 20/100. The original exclusive amount is the inclusive total minus its rounded VAT component. The step-by-step VAT guide explains that reverse calculation in detail.
An exclusive comparison can be informative, but it does not establish the economic cost after tax recovery. Do not label an amount as recoverable merely because the calculator separates VAT. This guide does not check registration, supporting documents, business use or recovery restrictions.
A four-question quote check
- Do both quotes cover the same quantity, specification and service period?
- Is each amount explicitly before or including VAT?
- Are delivery, installation and any other charges included on the same basis?
- Have you separated the inclusive price comparison from any claim about VAT recovery?
If one answer is missing, obtain the missing quote information before comparing. A calculator with tax is most useful when its starting assumptions are visible, not when it makes them for you.
This is a one-amount comparison, not an invoice validator. Mixed treatments, several invoice lines and special schemes require separate assessment. The tool rounds VAT first to cents as documented in the calculation methodology; displayed pennies can depend on aggregation and rounding scope. Professional tax review remains pending.
Frequently asked questions
Is a price plus VAT the final price?
No. If VAT applies, a plus-VAT price still needs its VAT component added. Confirm any delivery or other charges separately.
Can I subtract 20% from a VAT-inclusive quote?
Not to recover the original exclusive price at an assumed 20% treatment. Use the inclusive VAT fraction 20/120 and subtract the rounded VAT component.
Does a VAT amount prove that I can reclaim it?
No. Recovery depends on requirements outside this one-amount comparison. The calculator does not determine entitlement.
Can delivery change which quote is cheaper?
Yes. In the synthetic delivered example, A becomes GBP 312 including VAT and B becomes GBP 313. Compare the same included items before choosing the lower total.
What should I do if a quote does not say whether VAT is included?
Ask the supplier to confirm the VAT basis and any remaining charges in writing. A missing label is not evidence that VAT is zero or already included.
Use the same country engine
Add tax or extract the included amount with the calculation method used in these examples. Select the treatment applicable to your transaction separately.
UK VAT calculator